
ADVERTISEMENT
ADVERTISEMENT
Affirm feels built for shoppers who want buy now, pay over time without turning checkout into a confusing credit process.
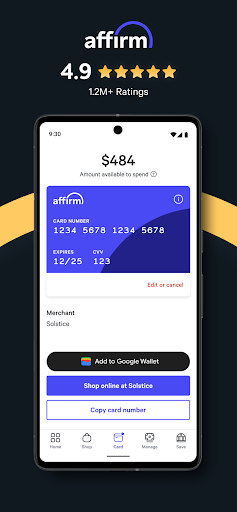
From my perspective, the strongest experience is how prominently the app surfaces purchasing power, expected options, and next steps.
Instead of hiding payment details, it brings the decision to the foreground, which reduces anxiety for first-time users.
In-store and online requests are both supported, so the workflow can stay consistent across purchases.
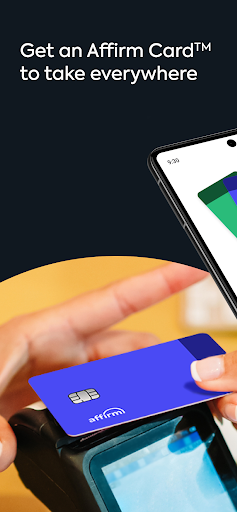
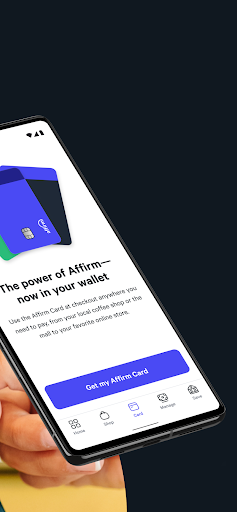
The app also supports an Affirm Card™ experience where you can use a Visa-accepted debit card in the U.S.
For eligible customers, the card angle matters because it expands where payment plans can be requested.
For brands and high-value cart sizes, the app communicates payment structure clearly, including plans that extend beyond 12 months.
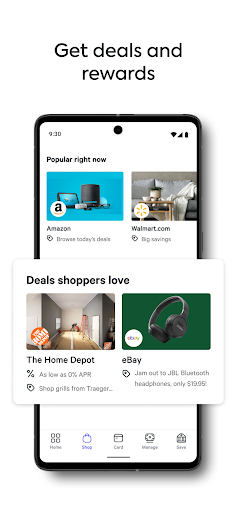
When deals or 0% APR options appear, the app frames them as selectable plans rather than vague promotions.
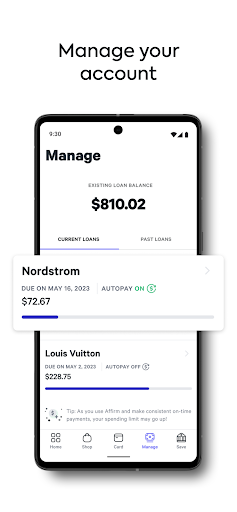
I liked that AutoPay is available, but the app also supports early or one-time payments when cash flow changes.
That flexibility is a practical fit for subscription management, SaaS renewals, and recurring business expenses.
However, the experience still relies on eligibility checks, minimum purchase rules, and plan matching per purchase.
So while the UI is friendly, the underlying system is selective, which may affect users with smaller or excluded transactions.
Overall, Affirm targets people evaluating financing for high-value purchases, including enterprise-style software subscriptions and durable goods.
The app’s main promise is straightforward: transparent options, online or in-store requests, and smoother payments for planned spending.
1) Clear purchasing power visibility helps users understand what they can afford before committing to checkout.
2) Flexible payment options include 0% APR choices, plan lengths over 12 months, and structured installments.
3) AutoPay plus manual control supports budgeting, early payments, and one-time payments when needed.
4) The Affirm Card™ approach lets eligible customers use a Visa-accepted debit card across the U.S. with payment plans.
1) Payment plans must be applied for each purchase, so users can’t assume the same terms will carry forward.
2) Minimum purchase amounts may block pay-over-time options, especially for low-ticket online purchases.
3) Approval and terms are not guaranteed, so eligibility checks can surprise users expecting instant financing.
4) If a purchase doesn’t match to a payment plan, an ACH debit may be initiated within 1-3 days, which needs careful monitoring.
Recent updates focus on making plan discovery faster, so users can find eligible offers and 0% APR options with less friction.
The newest flow places the card and payment plan experience more prominently, improving clarity around “request before or after checkout.”
Navigation improvements also help users manage payment schedules, including AutoPay setup and early payment actions.
Overall, the latest version refines how financing choices are presented, which benefits high-value shoppers comparing payment structures.
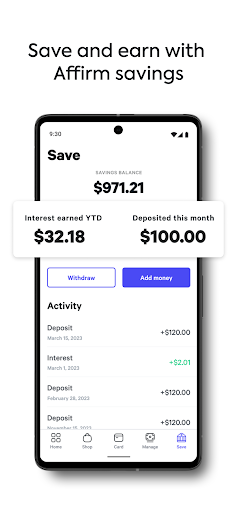
Affirm works best for users who want structured financing, transparent payment schedules, and a smoother way to budget big purchases.
If you value clear options for payments, subscriptions, and other higher-ticket needs, the app can feel genuinely practical.
Just remember that eligibility checks, minimum purchase requirements, and per-purchase plan application are real constraints.
With those expectations set, Affirm can be a solid tool for pay-over-time decisions that fit everyday purchasing and larger projects.


